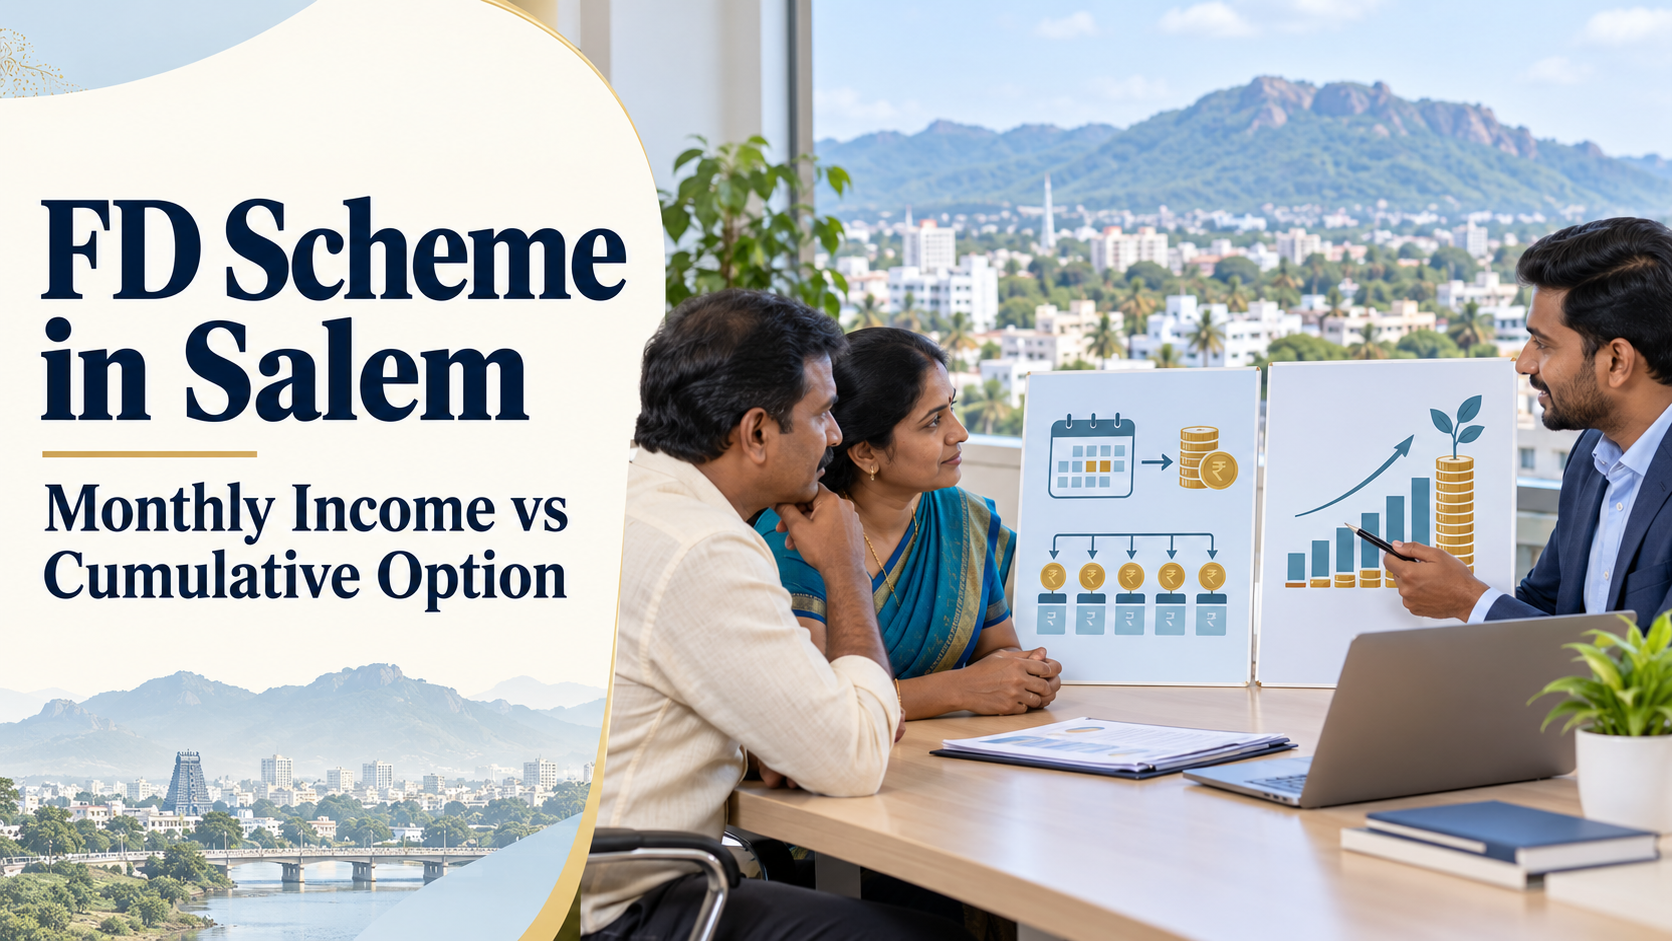
FD Scheme in Salem: Monthly Income vs Cumulative Option
Every FD scheme in Salem asks you one important question when you open it: do you want the interest paid out to you regularly, or do you want it to stay in the deposit and grow until maturity? The answer changes how much you receive, when you receive it and how well the deposit fits your household budget.
This guide compares the monthly income option with the cumulative option in plain terms. It is meant for families, shop owners, salaried people, homemakers and first-time depositors in Salem, Attur, Namakkal, Erode and Mettur who have a lump sum to place and want to choose the version that suits their cash flow.
We use hypothetical rates in every example, because actual rates change. For the current terms, check the YoursPay fixed deposit page or ask at the Salem branch.
Table of Contents
Two Ways an FD Scheme in Salem Can Work for You
A fixed deposit is the same basic product in both cases. You place a lump sum for a fixed tenure at a rate agreed on the day you book it. What differs is what happens to the interest along the way.
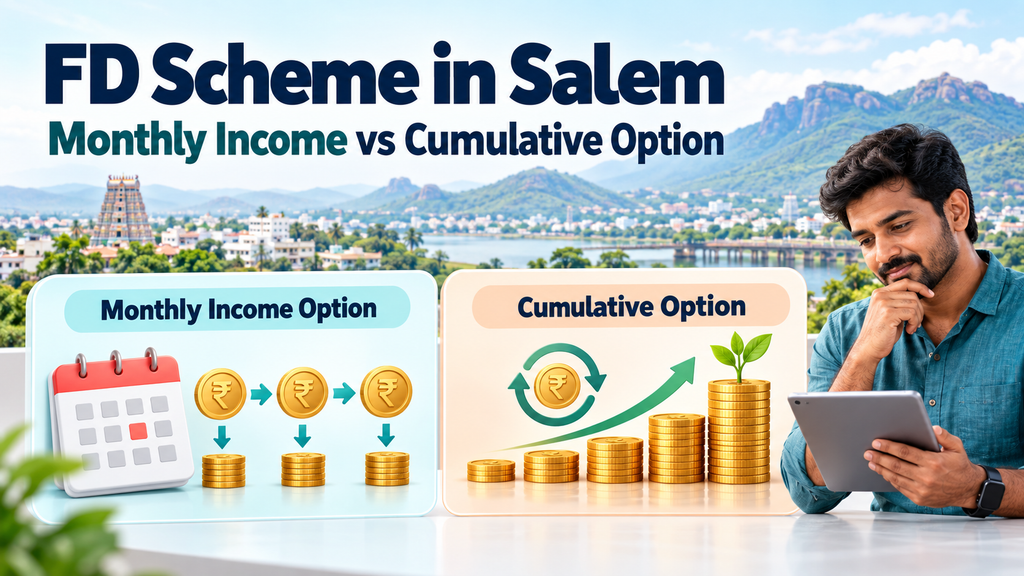
- Monthly income option: interest is paid out to you every month, usually into a savings account, and your principal stays the same until maturity.
- Cumulative option: interest is added back to the deposit, earns further interest, and the whole amount is paid at maturity.
Between these two sit the quarterly, half-yearly and yearly payout versions. At the time of writing, the YoursPay FD calculator shows five choices: at maturity (compound), monthly, quarterly, half-yearly and yearly payout. This article focuses on the two ends of that range, because that is where most depositors get stuck.
How the Monthly Income Option Works
With the monthly income option, the deposit behaves like a small, steady salary. Once the deposit is booked, a fixed amount of interest is credited to you each month for the whole tenure. At maturity, you get your original principal back.
A few practical points make a real difference:
- Credit date: ask which date of the month the interest is credited, so you can plan bills around it.
- Where it lands: interest usually goes to a savings account linked to the deposit, so keep that account active. Our page on the YoursPay savings account in Salem explains the account options.
- Exact amount: some institutions work out monthly payouts slightly differently from the annual rate, so the monthly figure may be a little lower than a simple one-twelfth. Ask for the exact rupee amount.
- No compounding: the interest you receive leaves the deposit, so it does not earn further interest inside it.
The strength of this version of an FD scheme in Salem is predictability. You know how much will arrive and when, which is useful for a household that runs on a monthly budget.
How the Cumulative Option Works
With the cumulative option, you receive nothing during the tenure. Instead, interest is added to your balance at regular intervals, and from then on that interest earns interest too. At maturity, you receive the principal plus all the interest in one payment.
This is where compounding does its quiet work. The longer the tenure and the more often interest is compounded, the wider the gap between a cumulative deposit and a payout deposit at the same rate. The YoursPay FD calculator page notes that its own formula uses annual compounding, so confirm how often your actual deposit compounds.
The cumulative option suits money with a clear future job, such as a college admission, a house repair or new equipment for a business. You do not touch it, and it arrives as one larger sum when you need it.
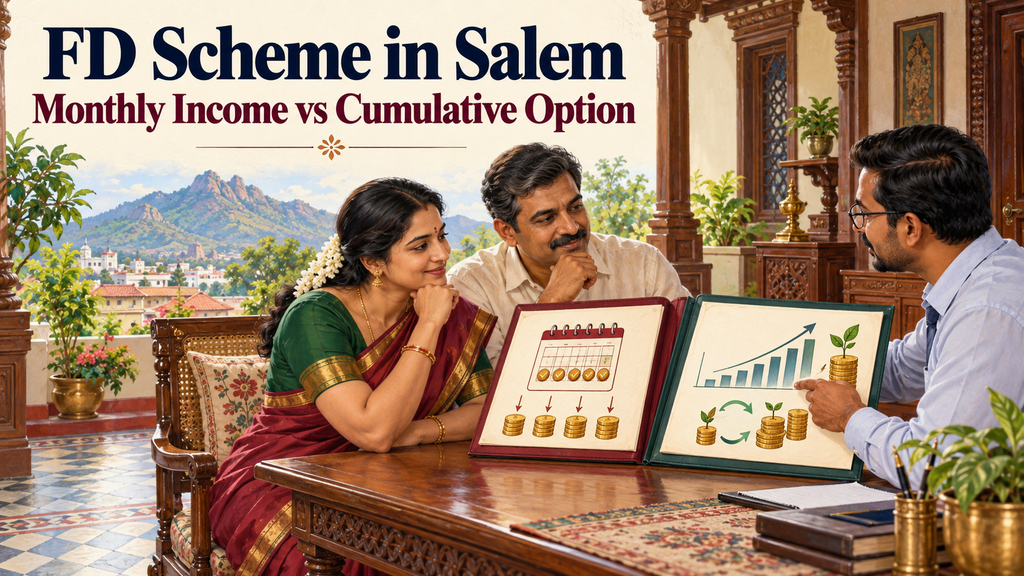
The Same Deposit, Two Results: A Worked Example
Say a family in Salem has Rs 3,00,000 to deposit for three years. To keep the comparison fair, both versions below use the same hypothetical rate of 7% a year. The cumulative figures assume yearly compounding.
| Detail | Monthly income option | Cumulative option |
|---|---|---|
| Deposit | Rs 3,00,000 | Rs 3,00,000 |
| Money received during the tenure | About Rs 1,750 every month | Nothing until maturity |
| Total interest over three years | About Rs 63,000 | About Rs 67,513 |
| Amount paid at maturity | Rs 3,00,000 | About Rs 3,67,513 |
| Best use | Regular household expenses | A goal with a fixed date |
The cumulative option ends about Rs 4,500 ahead in this example, because its interest keeps earning interest. If the same deposit compounded every quarter, the maturity amount would be about Rs 3,69,432, and the gap would widen to roughly Rs 6,400.
That gap is the price of receiving your money early. For a family that genuinely needs Rs 1,750 each month, it may be a fair price. For a family that lets the monthly credits pile up unused in a savings account, it is money left on the table.
Who the Monthly Income Option Suits
The monthly income option works best when the interest has a definite monthly purpose. These hypothetical situations show the kind of household that often benefits:
- A household with a fixed monthly gap: say a family in Erode needs a steady top-up for school fees paid in instalments or for a loan EMI. A monthly credit on a known date fills that gap neatly.
- A shop owner with uneven sales: a trader in Attur whose takings swing from month to month may like a small, predictable credit that does not depend on sales.
- A homemaker managing the kitchen budget: a separate monthly credit can cover groceries or utility bills without drawing on the main earner’s salary.
- Someone who has stopped working: a person who has retired or taken a career break may use monthly interest to replace part of a salary. Retirees can also read our senior citizen FD guide for Salem.
In each case, the monthly amount is spent on a planned expense. That is the test that separates a useful monthly income option from a habit that quietly costs you interest.
Who the Cumulative Option Suits
The cumulative option suits anyone who does not need income from this particular deposit and has a goal with a date. Common examples include:
- A salaried couple in Namakkal building a fund for a child’s college admission in three years.
- A family in Mettur planning roof repairs or a new floor after the monsoon.
- A business owner setting aside money to buy a machine or renovate the shop.
- A young earner parking a bonus or gift money that should not be spent.
Because nothing is paid until maturity, the cumulative option also has a behavioural benefit. The money is out of sight, so it is less likely to be spent on small things along the way.
If your goal needs regular saving rather than one lump sum, a recurring deposit may fit better. Our comparison of FD vs RD explains when each one makes sense.
A Quick Budget Test Before You Choose
Before you tick a box on the form, sit down with your monthly budget and answer these four questions honestly.
- Is there a monthly shortfall today? Add up regular income and regular expenses. If expenses are higher, the monthly income option can help close the gap.
- Will the shortfall last for the full tenure? If the gap is only for a few months, a monthly payout for three years may not be the right tool.
- Is there a dated goal for this money? If yes, and you have no shortfall, the cumulative option is usually the better fit.
- Will you actually spend the monthly amount on something planned? If the honest answer is no, choose the cumulative option and let the interest compound.
Many people choose a monthly payout simply because a regular credit feels comforting. The budget test helps you choose on purpose rather than on feeling.
The Middle Path: Splitting One Lump Sum
You do not have to put the whole amount into one FD scheme in Salem. Splitting a lump sum into two deposits lets you have some income and some growth at the same time.
Using the same hypothetical 7% rate, say the family above splits Rs 3,00,000 into two equal deposits:
| Deposit | Option | What it does (example) |
|---|---|---|
| Rs 1,50,000 | Monthly income | Pays about Rs 875 a month for regular bills |
| Rs 1,50,000 | Cumulative option | Grows to about Rs 1,83,756 in three years for a future goal |
In this example, the family still receives a useful monthly credit for small bills, while half of the money keeps compounding towards a larger goal. Neither half is locked into a choice that does not suit it.
The split can be adjusted to your own numbers. If your monthly need is small, place only as much as you need in the payout deposit and let the rest compound.
Quarterly or half-yearly payouts are another middle path. They suit expenses that come a few times a year, such as school term fees or insurance premiums, and they leave the money in the deposit a little longer between payments.
What to Do with Monthly Interest You Do Not Spend
Sometimes a household picks the monthly income option and later finds it does not need every credit. Instead of letting the money drift in a savings account, give it a job.
- Start a recurring deposit: a small monthly RD can recapture much of the growth you gave up. The YoursPay recurring deposit page explains how it works.
- Build an emergency buffer: keep a few months of expenses in an easy-to-reach savings account before anything else.
- Prepay costly debt: if you carry a high-interest loan, using spare interest to reduce it can make sense.
At renewal, review whether you still need a payout. If not, switching the next deposit to the cumulative option may be simpler than managing a second product.
Tax and Paperwork Points for Both Options
Choosing the cumulative option does not delay or remove tax on the interest. FD interest is generally taxable as part of your income, whether it is paid to you each month or added to the deposit, and tax may be deducted at source once interest crosses a limit set by the government.
Keep a simple file for each deposit with the receipt, the payout option chosen, the credit date and any tax certificates. For the current rules, see the Income Tax Department website or ask a tax adviser.
How Early Closure Affects Each Option
Plans change, and sometimes a deposit has to be closed before maturity. The two options behave differently when that happens, so it helps to understand the effect before you choose an FD scheme in Salem.
Many institutions recalculate interest at a lower rate when a deposit is closed early, often the rate for the period the money actually stayed, minus a penalty. With the cumulative option, that lower rate is simply applied to the balance, and you receive less than the maturity amount you were shown.
With the monthly income option, you have already received interest at the original rate. If the rate is revised downward on early closure, the extra interest already paid may be adjusted from the amount returned to you. Ask the branch to explain, in rupees, what you would receive if you closed after one year under each option.
If there is a real chance you will need part of the money early, consider keeping that part in a separate, shorter deposit or in your savings account instead.
Common Mistakes When Choosing a Payout Option
Most problems with a payout choice come from small oversights at the time of booking. Watch out for these:
- Choosing monthly payout out of habit: if you do not need the credit, the cumulative option usually leaves you with more at maturity.
- Forgetting that prices rise: a fixed monthly amount buys a little less each year, so do not rely on it to cover a growing expense for a long tenure.
- Using the cumulative option for near-term needs: money you will need within months is better kept where you can reach it without closing a deposit.
- Linking payouts to an inactive account: make sure the savings account that receives the interest is active and in the right name.
- Not writing down the maturity date: note it in your phone and on the deposit file so the money does not sit idle after maturity.
A few minutes spent on these points at the counter can make your FD scheme in Salem far easier to live with over its full tenure.
Questions to Ask Before You Pick an Option
Take these questions to the branch so there are no surprises later:
- Which payout options are available for my tenure and amount?
- For the monthly income option, what exact amount will I receive and on which date?
- For the cumulative option, how often is interest compounded, and what is my maturity amount?
- Can I change the payout option during the tenure, or only at renewal?
- What happens to each option if I close the deposit early?
- What happens at maturity if I give no instructions?
To see both options side by side for your own amount, enter the same deposit, tenure and rate into the YoursPay FD calculator, first with the monthly payout and then with payout at maturity. The results are indicative, so confirm the figures with YoursPay. For more on payout frequencies, read our guide to fixed deposit interest payouts.
Frequently Asked Questions
Which is better, the monthly income or the cumulative option?
Neither is better for everyone. The monthly income option suits planned monthly expenses, while the cumulative option usually builds a larger maturity amount for a dated goal at the same rate.
Does the monthly income option earn a lower rate?
The quoted annual rate may be the same, but the total interest is usually lower because monthly payouts do not compound. Some institutions also calculate monthly payouts slightly differently, so ask for the exact amount.
Can I switch from monthly payout to cumulative midway?
This depends on the institution. Many allow changes only at renewal, so choose carefully and confirm the rule before you book the FD scheme.
Where is the monthly interest credited?
It is usually credited to a savings account linked to your deposit. Confirm the account and credit date when you open the deposit.
Is tax lower if I choose the cumulative option?
No. FD interest is generally taxable in both cases. Speak to a tax adviser about how it applies to your income.
Can I have both options at the same time?
Yes. You can split your lump sum into two deposits, one with monthly payout and one with the cumulative option.
Want help choosing the right FD scheme in Salem for your household? Visit the YoursPay fixed deposit page or contact YoursPay to ask for a written quote for both options.
This article is general information, not financial advice. All rates and amounts in the examples are hypothetical. Payout options are taken from the YoursPay website at the time of writing and may change, so please confirm current rates and terms before you deposit.