Monthly Savings Scheme in Salem: 5 Options for Middle-Class Families
Choosing a monthly savings scheme in Salem is one of the most useful money decisions a middle-class family can make. A fixed amount set aside every month turns an irregular habit into a plan, and it keeps big expenses such as school fees, a wedding or a house repair from turning into a loan.
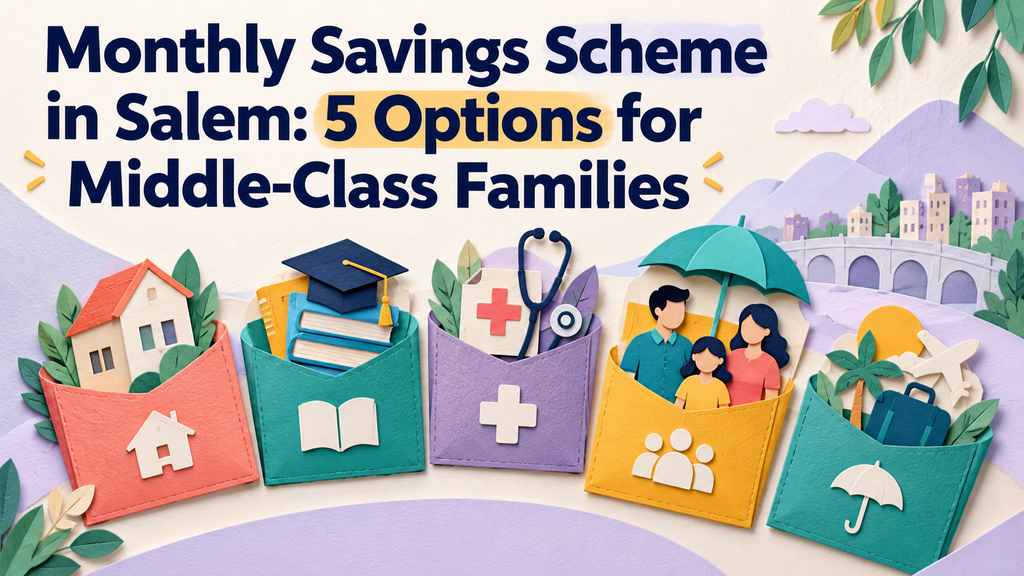
The trouble is that there are many choices, and each one is built for a different job. This guide walks you through five practical options, explains who each one suits, and shows how a family can combine them. It is written for salaried households, small traders and working couples in Salem, Attur, Namakkal, Erode and Mettur.
Where we mention YoursPay products, the details come from the YoursPay website at the time of writing. Rates and terms change, so confirm the current terms before you sign up for anything.
Table of Contents
What a Good Monthly Savings Scheme in Salem Should Do
Before comparing products, it helps to agree on what “good” means for a family budget. A monthly savings scheme is not only about the interest it earns. It must also fit your income, your goals and the way your household actually handles money.
Look for these qualities in any option you consider:
- An amount you can keep paying: even in a month with a hospital visit or a relative’s function.
- A clear goal and date: money saved for “something” is easy to spend on anything.
- The right level of access: emergency money must be reachable quickly, while goal money should be a little harder to touch.
- Simple rules: you should understand penalties, closure terms and tax without needing an expert.
- A provider you can check: know who holds your money, how it is regulated and where to complain if something goes wrong.
No single monthly savings scheme ticks every box for every goal. That is why most families do better with two or three options working together.
First, Find Your Monthly Surplus
A monthly savings plan built on a guess usually fails by the third month. Spend one evening working out what you can really set aside.
- List your take-home income for the month. If it varies, use the average of your three lowest months from the past year.
- Write down fixed costs: rent or home loan, school fees, electricity, groceries, travel, phone and any EMIs.
- Add a realistic figure for variable costs such as medicines, gifts, repairs and eating out.
- Subtract both totals from your income. The balance is your monthly surplus.
- Commit only about two-thirds of that surplus to your monthly savings. Keep the rest as a cushion.
If your income changes with the season, as it does for many traders and farmers around Salem, our guide on how to save money on an irregular income shows how to smooth out good and lean months.
Option 1: A Recurring Deposit for Fixed Goals
A recurring deposit, or RD, is the classic monthly savings scheme in Salem and across India. You choose an amount and a tenure, deposit that amount every month, and receive the total with interest at maturity. It suits goals with a known date one to three years away.
Why families like it:
- The instalment is the same every month, which makes budgeting easy.
- The goal date is built in, because the deposit matures on a fixed day.
- Interest is usually fixed for the tenure when you open it, so you can see the expected maturity amount in advance.
At the time of writing, the YoursPay recurring deposit in Salem is offered as a General Citizen RD and a Senior Citizen RD, with tenures of 1, 2 and 3 years. The page states that rates are approximate and subject to change, so check the current rate there and try your figures on the RD calculator.
Keep in mind that RD interest is taxable, and missed instalments may bring a penalty and reduce the maturity value. For a fuller introduction, see our guide to the recurring deposit in Salem.
Option 2: A Savings Account With a Fixed Monthly Transfer
Every family needs money it can reach quickly. A savings account is the natural home for this emergency fund. The trick is to treat it like a monthly savings scheme: move a fixed amount into it on the same date every month and do not use it for routine spending.
A common target is an emergency fund equal to three to six months of essential household costs. Build it slowly. Even a modest transfer each month adds up over a year or two.
The YoursPay savings account page currently lists three tiers:
| Account | Opening and holding amount | Monthly cash deposit limit | Monthly cash withdrawal limit |
|---|---|---|---|
| Savings Account | Rs 100 | Rs 2,00,000 | Rs 1,00,000 |
| Lakshmi Gold | Rs 500 | Rs 5,00,000 | Rs 2,00,000 |
| Gubera Lakshmi | Rs 1,000 | Rs 10,00,000 | Rs 5,00,000 |
Each tier comes with a physical passbook and nominee support. The page lists four documents for opening: Aadhaar and PAN copies with your signature, the nominee’s Aadhaar copy with their signature, and two passport-size photographs. Over-limit charges apply beyond the monthly limits, so ask for the full terms.
Option 3: A Child Savings Plan for Long-Term Goals
Children’s higher studies and marriage are the biggest planned expenses for most middle-class families, and they are usually ten or more years away. A plan built for a child keeps this money separate from everyday savings.
At the time of writing, the YoursPay child savings scheme lists three plans. Plan A and Plan B take a monthly saving for 60 months, starting from Rs 1,000 a month, with the payout arriving over a ten-year horizon. Plan C is a one-time lump sum with a monthly dividend, for families who already hold a larger amount.
Before choosing any child plan, ask these questions:
- How many years will the money be locked in, and what happens if you need it early?
- Are the maturity figures shown fixed, or are they indicative and subject to change?
- Who operates the account until the child comes of age?
- Which documents are needed for the parents, the child and any guardian?
The YoursPay page notes that all figures are approximate and asks customers to confirm current scheme details and charts at the Salem branch. Do that before you commit.
Option 4: Post Office and Government Small Savings Schemes
Many families in and around Salem save through the post office. India Post offers a recurring deposit of its own, along with other small savings schemes for different goals, and there is a post office within easy reach of most neighbourhoods and villages in the district.
These schemes are popular with savers who value a government-run channel and a familiar local counter. Their interest rates are set by the government and revised from time to time, so check the current figures on the India Post website or at your nearest post office rather than relying on an old passbook.
Points to compare if you are weighing a post office scheme against other options:
- The minimum monthly amount and the fixed tenure of each scheme
- Rules for missed instalments and early withdrawal
- How and where you can deposit each month
- Tax treatment of the interest
Option 5: A Monthly SIP in Mutual Funds
A systematic investment plan, or SIP, puts a fixed amount into a mutual fund every month. Unlike the first four options, a SIP is market-linked. The value of your investment can rise and fall, and there is no fixed maturity amount.
A SIP may suit part of your savings if:
- Your goal is at least five to seven years away, such as retirement or a child’s college fees.
- You already have an emergency fund and fixed-goal savings in place.
- You are comfortable seeing your balance fall in a bad year without stopping your instalments.
Mutual funds are regulated by the Securities and Exchange Board of India. Before you start, read the investor education material on the SEBI website and invest only through a registered platform or distributor. You can estimate long-term growth with the SIP calculator, but remember that any return you enter is an assumption, not a result.
Comparing the Five Options Side by Side
The table below puts the five options on one page. Use it to match each rupee of your savings to the right job, rather than looking for one perfect monthly savings scheme.
| Option | Best suited for | Typical time frame | Access to money | Nature of return |
|---|---|---|---|---|
| Recurring deposit | Known goals with a date | 1 to 3 years | At maturity; early closure may reduce interest | Rate usually fixed for the tenure |
| Savings account with fixed transfer | Emergency fund | Ongoing | Anytime, within account limits | Lower, variable |
| Child savings plan | Education and marriage | 10 years or more | Locked in as per plan terms | As per plan; check if indicative |
| Post office schemes | Steady saving through a government channel | Varies by scheme | As per scheme rules | Set by government, revised periodically |
| Mutual fund SIP | Long-term wealth building | 5 years or more | Usually redeemable, value varies | Market-linked, can go up or down |
A Sample Split for a Salem Family
Here is an example, not a recommendation. Say a couple in Salem has worked out a comfortable monthly surplus of Rs 6,000. Their son starts college in about eight years, they want to renovate the kitchen in two years, and they have no emergency fund yet.
- Rs 2,000 a month to the savings account until the emergency fund reaches about three months of expenses.
- Rs 2,000 a month into a two-year RD for the kitchen renovation.
- Rs 2,000 a month towards the son’s education, through a child savings plan, a long-term SIP or a mix of both, depending on their comfort with market ups and downs.
Once the emergency fund is complete, the Rs 2,000 that went into the savings account can be moved into a new goal, such as a fresh RD or a larger education contribution. This way the family keeps the same monthly savings habit while the goals change over time.
Different families will split their monthly savings differently. A household with elderly parents may put more into the emergency fund. A family with a daughter’s wedding in three years may put more into RDs. The principle stays the same: one job for each part of your monthly savings.
Questions to Ask Before Joining Any Monthly Savings Scheme
Whichever option you pick, the same set of questions protects your money. Ask them at the counter, write down the answers and keep them with your passbook or receipts.
- Who is offering this scheme? Note the full legal name of the provider, not just the brand name on the board.
- How is it regulated? Ask which authority oversees the provider and what protection, if any, applies to your deposit.
- What is the current rate or expected return? Ask whether it is fixed for your full tenure or can change.
- What happens if I miss a month? Get the penalty terms and how many missed instalments are allowed.
- Can I close early? Ask what rate applies if you withdraw before maturity.
- How is tax handled? Ask whether tax is deducted at source and what paperwork you will receive.
- Where do I complain? Note the grievance process and the phone number or email for complaints.
A trustworthy provider will answer all of these clearly. If you get vague replies, pressure to sign quickly, or promises of unusually high returns, walk away and compare another monthly savings scheme before you decide.
For YoursPay products, the website has a grievance redressal page that explains how to raise a concern.
Mistakes Middle-Class Families Often Make
Most savings plans fail for simple reasons, not because the family chose the wrong product. Watch for these patterns.
- Starting too big: an ambitious amount that has to be skipped in month four is worse than a smaller amount paid every month.
- Using goal money for emergencies: breaking an RD for a medical bill costs interest and derails the goal. Build the emergency fund first.
- Chasing the highest figure: a slightly higher rate is not worth it if you do not understand the provider or the closure rules.
- Keeping everything in cash at home: it earns nothing and is easily spent or lost.
- Not writing anything down: keep a simple list of every scheme, its amount, its maturity date and its nominee, and tell your spouse where it is kept.
For more ideas on building a family plan, read our overview of the best savings plans for families in India.
Simple Steps to Start This Month
You do not need to set up all five options at once. Start with one monthly savings scheme, make it a habit, then add the next.
- Work out your monthly surplus using the steps above.
- Open or reuse a savings account and set a fixed transfer date for the emergency fund.
- Pick your nearest goal with a date, and choose an RD tenure that ends just before it.
- Collect your Aadhaar, PAN, nominee details and photographs before visiting any provider.
- Ask each provider for the current rate, penalty terms and closure rules in writing.
- Review your plan every six months, or whenever your income or goals change.
Protect your savings from fraud as well. Never share an OTP, PIN or password with anyone who calls claiming to be from a bank or finance company. If you are targeted, report it on the national cyber crime reporting portal.
Frequently Asked Questions
Which monthly savings scheme in Salem suits a middle-class family best?
There is no single answer. Most families do well with a savings account for emergencies, a recurring deposit for goals within three years and a long-term option for education or retirement.
How much should we save every month?
Start with about two-thirds of your real monthly surplus after fixed and variable costs. Increase it when your income rises or a loan is closed.
Is a recurring deposit better than a SIP?
They do different jobs. An RD suits short, fixed goals where you want a known maturity amount. A SIP is market-linked and suits long goals where you can accept ups and downs.
What documents are needed to open a YoursPay savings account?
The YoursPay savings account page lists Aadhaar and PAN copies with your signature, the nominee’s Aadhaar copy with their signature, and two passport-size photographs.
Where can I check the current YoursPay RD rate?
Check the YoursPay recurring deposit page, try your numbers on the RD calculator, and confirm the rate at the Salem branch, since rates are approximate and can change.
Can I start a monthly savings scheme with a small amount?
Yes. The YoursPay savings account starts from Rs 100, and the child savings plans start from Rs 1,000 a month. Starting small and staying regular matters more than the size of the first instalment.
Ready to put your monthly savings to work? Explore the YoursPay recurring deposit or contact the Salem team to discuss a plan that fits your family budget.
This article is general information, not financial advice. The family example is hypothetical. YoursPay product details are taken from its website at the time of writing and may change. Please confirm current rates and terms before you invest.