Separate Business and Personal Finances: 8 Simple Steps
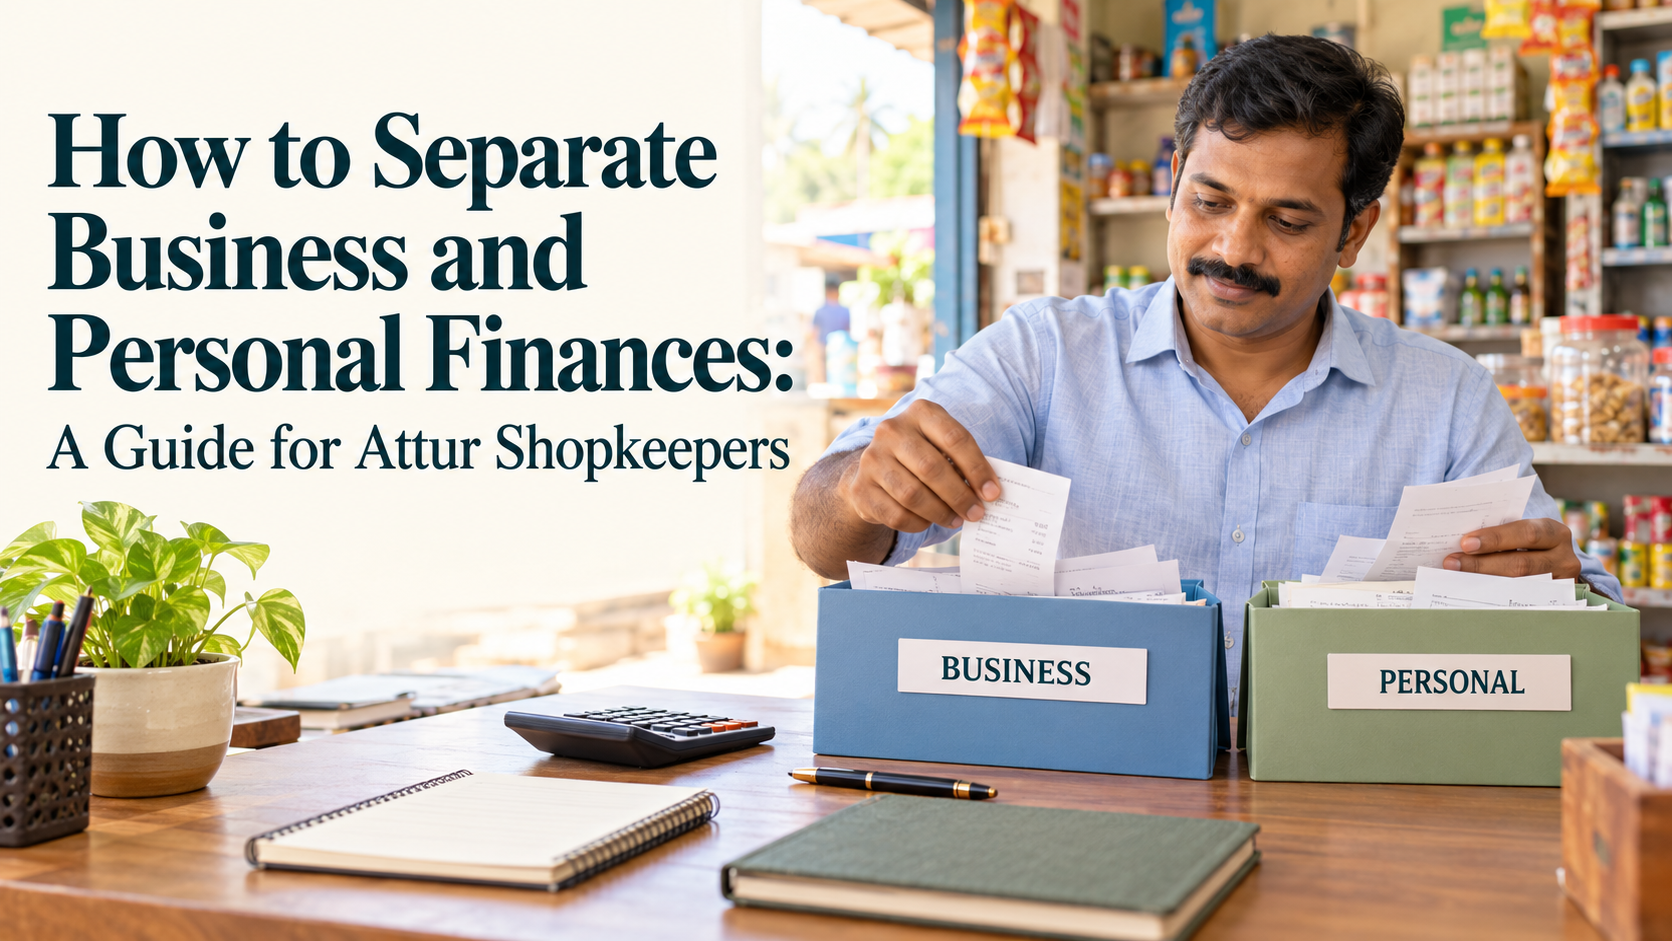
How to Separate Business and Personal Finances: A Guide for Attur Shopkeepers
A customer pays for groceries. A few minutes later, money from the same cash drawer goes towards a household purchase. By evening, the shop has made sales, paid a supplier and covered several family expenses—but nobody is sure how much the business has actually earned.
This is a familiar problem for small shops. Learning to separate business and personal finances starts with making those movements visible.
For shopkeepers in Attur, a simple system can help protect stock money, organise household withdrawals and reduce confusion at the end of the month. You do not need complicated software to begin. Separate records, an appropriate business account and a short daily review can make a useful difference.
Why Shop Collections Are Not Personal Income
Money arriving at the counter may already have a purpose.
Some will be needed to replace stock. Some may be due to suppliers. Rent, wages, electricity and other commitments still have to be paid.
Keep these terms separate:
| Term | What it means |
|---|---|
| Sales | The value of goods or services sold |
| Collections | Money actually received, including payments for earlier credit sales |
| Profit | Revenue less the relevant costs and expenses |
| Available cash | Money currently held in cash or bank accounts |
| Owner withdrawal | Money taken out for the owner’s personal use |
A busy shop can still have a cash shortage. A large bank balance can also include borrowed money, unpaid supplier amounts or an owner’s personal contribution.
Separating finances helps you understand these differences before spending.
1. Choose a Clear Starting Date
Pick a date from which you will record business and household transactions separately. The first day of a week or month can be convenient.
On that date, write down:
- Cash physically available in the shop.
- Balances in accounts used for business.
- Customer payments still outstanding.
- Supplier bills still unpaid.
- Upcoming rent, wages and other commitments.
- Any personal money recently introduced into the business.
Do not describe all the opening cash as profit.
If older records are mixed, preserve them and ask your accountant to help classify important entries. You can start a better daily routine now while correcting earlier records separately.
2. Use an Account Suitable for Business Transactions
Ask your bank which account is appropriate for your shop’s activity. Do not assume that a second personal savings account permits regular commercial transactions.
A business current account is worth discussing, particularly if you receive frequent collections, pay suppliers and deposit cash regularly.
Compare:
- Minimum or average balance requirements.
- Cash-deposit allowances and charges.
- Transfer facilities.
- Statement access.
- Merchant-payment compatibility.
- Branch convenience and support.
For an example of the features banks publish, see SBI’s current-account comparison. Check the current terms directly before choosing.
Use the business account for shop transactions and your personal account for household spending. Separate accounts improve recordkeeping, but they do not replace proper books or create a separate legal entity for a sole proprietor.
3. Direct Shop Payments to the Correct Account
Check which account receives payments from the QR code displayed at your counter.
If customer payments go into a personal account used for groceries, family transfers and subscriptions, identifying sales becomes harder.
Ask your bank or payment provider to arrange a merchant setup suitable for your business. Confirm the settlement account, charges, timing and refund process.
For every digital payment:
- Check the transaction status through your own trusted merchant app or bank records.
- Match the payment with the sale.
- Record refunds, reversals and pending settlements separately.
- Investigate differences before treating the amount as available cash.
A payment soundbox may help staff notice incoming payments, but it does not replace reconciliation.
You can review the YoursPay soundbox information page when comparing payment-alert services. Confirm account compatibility, fees, settlement arrangements and support before signing up.
Never rely only on a customer’s payment screenshot.
4. Plan Household Withdrawals Instead of Taking Cash at Random
Set a weekly or monthly amount for household use based on what the business can reasonably support.
First allow for stock, suppliers, shop expenses, debt commitments and upcoming statutory payments. Then assess what can be withdrawn without creating a shortage.
For a sole proprietor, money taken for personal use is generally recorded as drawings, rather than as an operating expense or a salary paid to oneself.
For partnerships, LLPs and companies, owner-related payments can require different treatment and authorisation. Ask your accountant how to record them.
A practical family rule
Agree that every household withdrawal will be recorded, even if it is small.
For example:
“We will make one planned household transfer each week. Any extra amount taken from the shop will be entered in the withdrawal record.”
This helps family members understand what is available without repeatedly using stock money.
A planned withdrawal is a target, not a guarantee. Review it if collections weaken or business commitments increase.
5. Record Personal Payments and Business Payments Correctly
Mixed payments can happen. The important step is to identify them rather than hide them within shop expenses.
| Situation | Recordkeeping action |
|---|---|
| Household groceries paid from shop cash | Record as an owner withdrawal, not a shop expense |
| Stock bought using the owner’s personal money | Keep the invoice and record the owner-funded business purchase correctly |
| Personal money transferred into the shop account | Identify it as an owner contribution or other appropriate funding entry, not a sale |
| Shop cash deposited into the business bank account | Record a transfer between cash and bank; do not count another sale |
| Money received from a customer for an old credit bill | Link it to that customer’s outstanding balance |
| Loan received into the business account | Record borrowing, not sales income |
Your accountant should determine the exact ledger treatment, especially where reimbursement, tax or business structure affects the entry.
If your family takes goods from shop stock for home use, record that too. Ask the accountant how the stock and any applicable tax treatment should be handled.
6. Keep One Daily Cash Record
A notebook or spreadsheet can work if entries are complete and consistent.
Use these columns:
Date | Description | Money in | Money out | Category | Payment method | Reference
At closing time, count the cash and compare it with the record.
Illustrative daily cash reconciliation
| Entry | Amount |
|---|---|
| Opening cash | ₹3,000 |
| Add: cash sales | ₹8,000 |
| Less: supplier payment | ₹5,000 |
| Less: shop expense | ₹500 |
| Less: owner withdrawal | ₹1,000 |
| Expected closing cash | ₹4,500 |
If you also received ₹6,000 through UPI, reconcile it separately with the relevant digital records. Do not add it to the physical cash count.
The ₹4,500 closing cash is not the day’s profit. Stock costs, credit sales, unpaid expenses and other entries may affect profitability.
If the cash count differs, investigate the missing entry. Do not automatically label the difference as a business expense.
7. Protect Working Capital and Keep Household Reserves Separate
Working capital supports the shop’s everyday activity. It helps pay for inventory, suppliers and operating expenses before all customer money has arrived.
Your household emergency reserve has a different purpose.
Keep separate records for:
- Business operating money.
- Funds reserved for known business commitments.
- Household spending.
- Personal emergency savings.
You do not necessarily need a separate bank account for every category, but you should know how much is reserved and why.
Do not use a fixed percentage for taxes without checking your situation. Ask your accountant to estimate the relevant obligations and due dates.
For household planning, SEBI’s guidance on managing income and expenses explains the value of budgeting, prioritising essentials and preparing for unexpected costs.
If you are considering a product listed on the YoursPay savings information page, first verify the legal provider, authorisation, withdrawal conditions and applicable protection. Do not assume it is a business transaction account.
8. Review Collections, Credit and Upcoming Bills Every Week
Choose a regular time to review the shop’s money.
A weekly review should answer:
- How much money was actually collected?
- Which customers still owe money?
- Which supplier bills fall due next?
- How much stock needs replacing?
- How much did the household withdraw?
- Are digital settlements and bank entries reconciled?
- What remains available after commitments?
Record credit sales when they happen and maintain a customer balance. When the customer pays later, reduce that outstanding balance instead of recording the same sale twice.
Keep supplier records in the same way. A payment made this week may relate to goods purchased earlier.
Back up digital records and retain invoices, receipts and statements so entries can be checked later.
A Weekly Planning Example for an Attur Shopkeeper
Imagine a shop has collected ₹50,000 during a week and is deciding how to allocate it.
| Planned use | Illustrative amount |
|---|---|
| Stock and supplier commitments | ₹28,000 |
| Shop operating payments | ₹8,000 |
| Provision for known statutory payments, based on an estimate | ₹3,000 |
| Planned owner withdrawal | ₹6,000 |
| Business cash retained | ₹5,000 |
| Total allocated | ₹50,000 |
This is a cash-allocation example, not a profit statement or a recommended split for every shop.
The shopkeeper should also consider opening balances, earlier debts, customer credit and commitments beyond the week.
If collections fall, the household withdrawal may need adjustment. Taking the usual amount despite a shortage can leave the shop unable to replace stock.
Common Mistakes to Avoid
Counting every bank credit as sales
Owner contributions, loans and transfers between accounts are not customer sales.
Treating every payment as an expense
Owner withdrawals, loan-principal repayments and equipment purchases may require different accounting treatment.
Counting a cash deposit twice
Depositing cash already recorded as a sale moves money from the till to the bank. It does not create new revenue.
Using sales alone to decide household spending
High turnover does not necessarily mean high profit or spare cash.
Keeping records only when tax filing approaches
Small daily entries are easier to verify while the transaction is still fresh.
Sharing banking passwords with everyone helping at the counter
Use authorised access arrangements and clear responsibilities. Staff should not need the owner’s personal banking credentials to operate the shop.
A Seven-Day Plan to Separate Business and Personal Finances
| Day | Action |
|---|---|
| Day 1 | Record opening cash, bank balances, customer dues and supplier commitments |
| Day 2 | Discuss an appropriate business account with your bank |
| Day 3 | Check merchant QR and settlement-account details |
| Day 4 | Start the daily cash and digital-payment records |
| Day 5 | Agree on a realistic household-withdrawal routine |
| Day 6 | Organise invoices and identify mixed transactions |
| Day 7 | Reconcile the records and review upcoming payments |
This is a starting plan, not a deadline for bank approvals. Continue recording separately while any account setup is being completed.
Frequently Asked Questions
How can a small shop separate business and personal finances?
Use an account suitable for business activity, record shop transactions separately and make planned household withdrawals. Reconcile cash and digital collections regularly.
Is a second savings account enough?
Not necessarily. Ask the bank whether the account permits your intended commercial transactions and whether a current account is more appropriate.
Can I pay a supplier from my personal account?
If it happens, retain the invoice and record the owner-funded payment properly. Do not leave it out of the business records or claim the expense twice.
How much should I withdraw for household expenses?
Base the amount on sustainable cash availability after business commitments. There is no suitable fixed percentage for every shop.
Are owner withdrawals a business expense?
For a sole proprietor, personal withdrawals are generally drawings, not operating expenses. Other business structures require separate consideration.
Does a payment soundbox maintain my accounts?
No. It provides payment alerts. You still need to match transactions, check settlements and record sales, expenses, refunds and withdrawals.
Start with the Next Transaction
You can begin to separate business and personal finances without waiting for a new financial year.
Record the next sale correctly, note the next household withdrawal and check the day’s closing cash. Repeat the routine until it becomes part of closing the shop.
For Attur shopkeepers, clearer records can make supplier planning and household budgeting easier—and help an accountant identify problems before they grow.
For questions about a service listed on YoursPay, contact YoursPay. You can also visit the YoursPay blog for related money-management articles.
This article provides general financial and bookkeeping education. Examples are illustrative. Account eligibility, accounting entries and tax treatment depend on your business structure and circumstances; confirm them with your bank and accountant.